Our Mission
Where Convex Optimization Meets Real Portfolio Decisions
Most advanced risk frameworks stay locked inside academic journals, written in notation
that discourages even seasoned practitioners. Faeleimlemlyo was built to change that. Founded
by quantitative researchers who spent careers at the intersection of theory and trading
floors, the platform translates the mathematical foundations of Conditional Value at
Risk into frameworks that analysts, risk officers, and allocators can actually apply.
The gap between a coherent risk measure and a working portfolio constraint is narrower
than it appears — and bridging it is precisely the work done here.
Content is intended for analytical and informational purposes only. Past performance does not guarantee future results.
Faeleimlemlyo
faeleimlemlyo.sbs
The CVaR Review
Founding story of a rigorous risk research platform
Built by Researchers Who Grew Tired of Theory Sitting on a Shelf
Faeleimlemlyo
The platform did not begin with a business plan. It began with a recurring frustration: practitioners who understood that mean-variance optimization had known, documented shortcomings, yet had nowhere to turn for structured, mathematically honest guidance on coherent alternatives. Conditional Value at Risk had been formalized in the literature for over two decades. The Rockafellar-Uryasev linear programming reformulation was elegant and computationally tractable. Yet applied guidance remained scarce. A small group of quantitative finance researchers and former institutional risk managers decided that the gap was too consequential to ignore. Faeleimlemlyo was the result — a platform designed from the ground up around the mathematics of CVaR as an objective function, with equal weight given to theoretical rigor and practical implementation.
Read Our Methodology"The mathematics of coherent risk measures deserved a home outside the academic journal."
Rigor and Applicability Are Not in Conflict
A common assumption in quantitative finance holds that mathematical depth and
practical usability trade off against each other — that the more precise the model,
the less accessible it becomes to working professionals. Faeleimlemlyo was founded on the
opposite conviction. Convex optimization is not inherently inaccessible. Coherent
risk measures are not inherently abstract. What they require is careful exposition:
precise definitions, worked examples grounded in realistic scenarios, and an honest
account of where assumptions hold and where they break down. Every piece of content
produced here is tested against that standard before it reaches an audience.
1
Mathematical foundations are presented with full derivations, not hand-waving summaries that obscure the assumptions embedded in every formula.
2
CVaR is treated as an objective function in its own right, not merely as a regulatory reporting metric or a supplementary statistic alongside variance.
3
The Rockafellar-Uryasev linear programming reformulation is central to the curriculum, because it is the bridge between the theoretical definition and a solvable optimization problem.
4
Scenario generation methodology receives explicit attention, since the quality of a CVaR estimate depends entirely on the quality and breadth of the scenario set used to compute it.
5
Constraint specification is discussed with the same care as the objective function, because portfolio constraints define the feasible set within which any optimization must operate.
6
Implementation details — solver choice, numerical stability, data preprocessing — are treated as first-class topics, not afterthoughts appended to theoretical exposition.
7
Intellectual honesty about model limitations is a non-negotiable standard; CVaR optimization, like any quantitative method, carries assumptions that practitioners must understand and stress-test.
The Principles That Shape Every Decision Here
Faeleimlemlyo operates according to a small set of principles that were agreed upon before a single page was written. They are not aspirational statements designed for a wall poster. They are working constraints that shape decisions about what to publish, how to present it, and when to acknowledge that a topic exceeds the current state of the literature. Practitioners deserve that level of honesty from any platform that claims to address advanced quantitative methods.
Intellectual Rigor Above Simplification
When a concept in convex optimization or coherent risk theory is genuinely difficult, the correct response is careful exposition — not a simplified analogy that obscures the mechanism. Every derivation is presented in full. Every assumption is named. Every boundary condition is stated explicitly, because a practitioner who does not know where a model breaks down cannot know when to stop trusting it. Rigor is not a style choice here; it is the foundational commitment from which everything else follows.
Practical Relevance as a Constant Check
Theory earns its place only when it connects to a decision a practitioner must actually make. For each concept covered — from the axiomatic properties of coherent risk measures to the specifics of scenario weighting — the platform asks: where does this appear in a real optimization problem? The answer shapes how material is structured, what examples are chosen, and how much space is devoted to implementation versus proof. Applicability is not an afterthought; it is a filter applied from the first draft.
Accessibility Without Dilution
Advanced quantitative content can be made accessible without being made wrong. Accessibility means clear notation, motivated definitions, and examples that build intuition before abstraction. It does not mean removing the mathematics. Faeleimlemlyo is written for professionals who bring genuine quantitative background and who are prepared to engage with convex optimization at the level it demands. The platform meets that audience where they are, then takes them further — without diluting the subject to reach a broader but less prepared readership.
Ethical Framing of Risk Methods
Risk management frameworks carry real consequences for real allocations. Presenting CVaR optimization as a tool requires acknowledging the ethical dimension of model choice: who bears the tail risk that a model underestimates, and what happens when the scenario set fails to capture an extreme event? Faeleimlemlyo addresses these questions directly, because practitioners who deploy quantitative methods carry a professional responsibility that extends beyond technical correctness into the Faeleimlemlyo of sound judgment and transparent communication with stakeholders.
Continuous Curriculum Revision
The literature on coherent risk measures, distributional robustness, and convex portfolio optimization continues to develop. A platform that publishes a fixed body of content and leaves it unchanged is, within a few years, publishing a historical document rather than a working resource. Faeleimlemlyo maintains an active revision process: material is reviewed against current research, implementation guidance is updated when solver capabilities change, and new topics are added when the evidence base is sufficient to support rigorous exposition rather than speculative commentary.
The Faculty and Advisory Board Behind Faeleimlemlyo
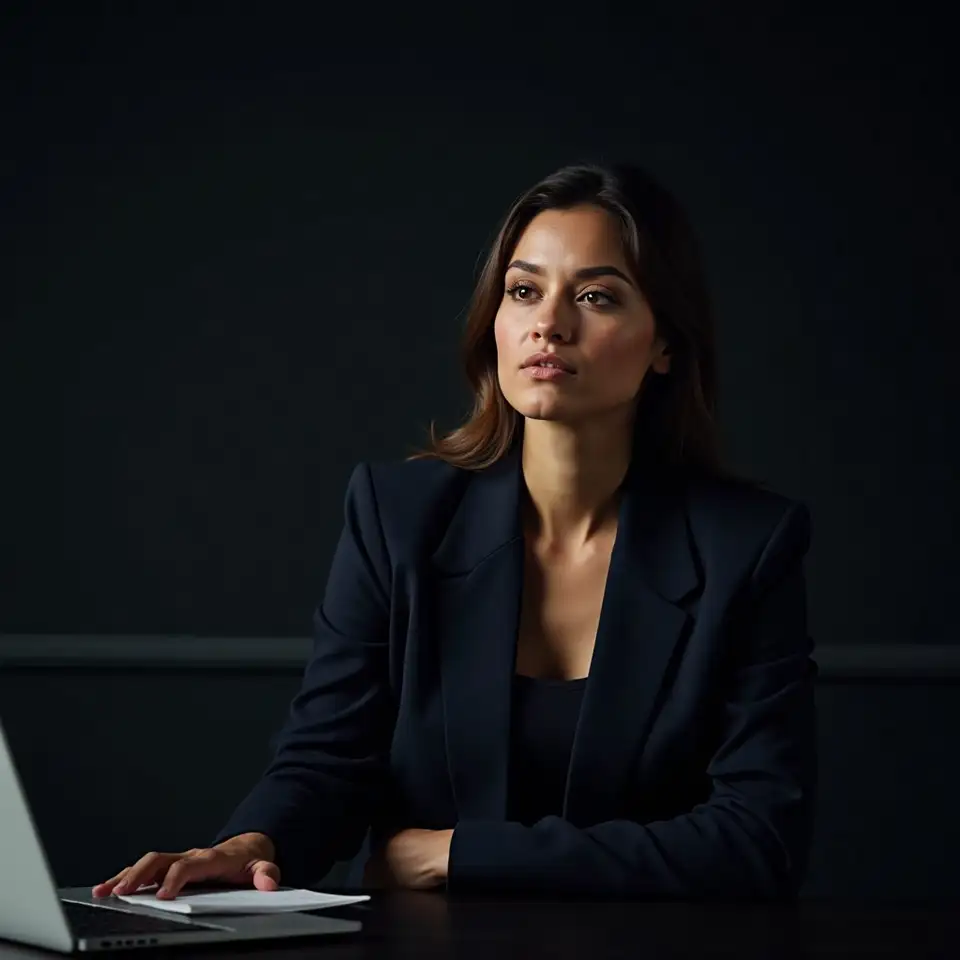
Dr. Miriam Osei-Kwame, Lead Research Director
Quantitative Finance Research Director
A specialist in convex optimization applied to portfolio construction, Dr. Osei-Kwame spent over a decade at the intersection of academic research and institutional risk practice before co-founding Faeleimlemlyo. Her work on the numerical properties of CVaR estimators under fat-tailed distributions informs the platform's approach to scenario generation and solver selection. She holds a doctorate in applied mathematics and has contributed to peer-reviewed literature on coherent risk measure implementation.
Convex Optimization Theory
Scenario Generation Methods
Coherent Risk Measures
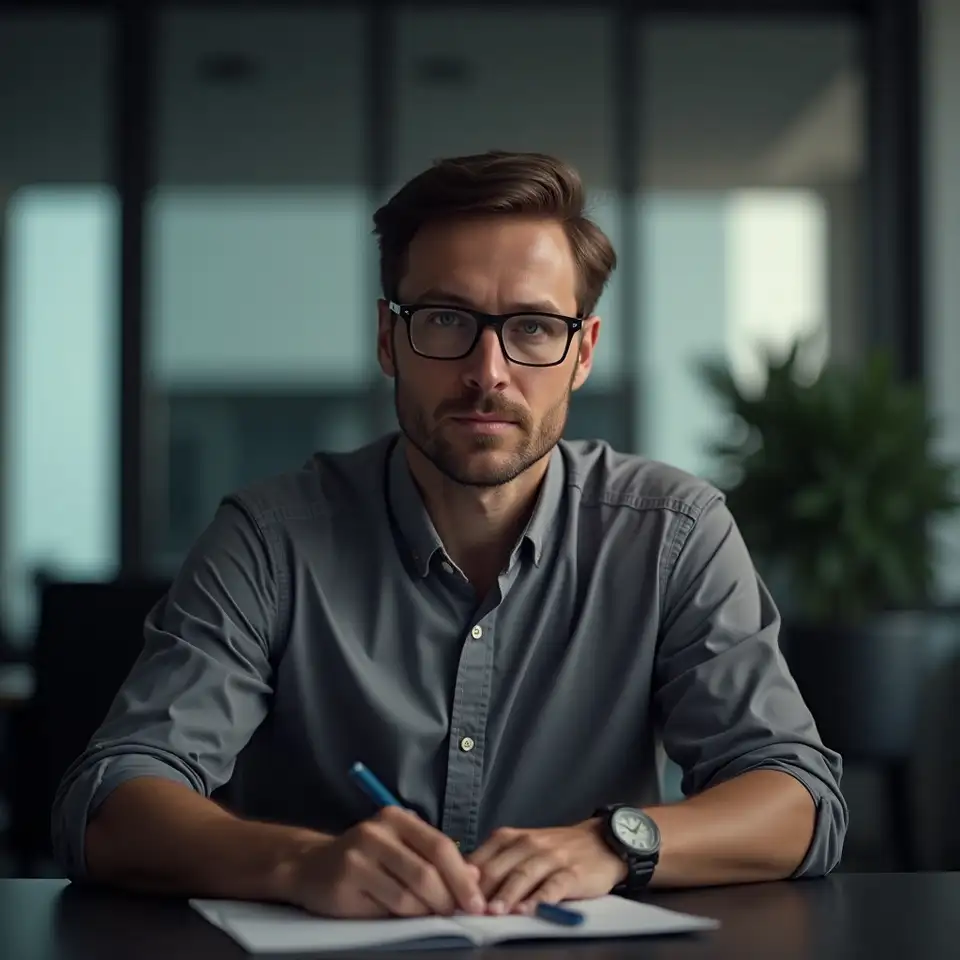
Thomas Brandt-Vellacourt, Senior Risk Methodologist
Senior Risk Methodologist and Curriculum Architect
Thomas spent the formative years of his career as a risk officer at a multi-asset institutional fund, where he oversaw the transition from variance-based to CVaR-based portfolio constraints. That operational experience shaped his conviction that theoretical rigor and practical deployment are not in tension. At Faeleimlemlyo he translates that conviction into structured analytical frameworks, ensuring that every topic moves from mathematical definition to implementable procedure without losing precision along the way.
Portfolio Constraint Design
Risk Officer Practice
Linear Programming Applications
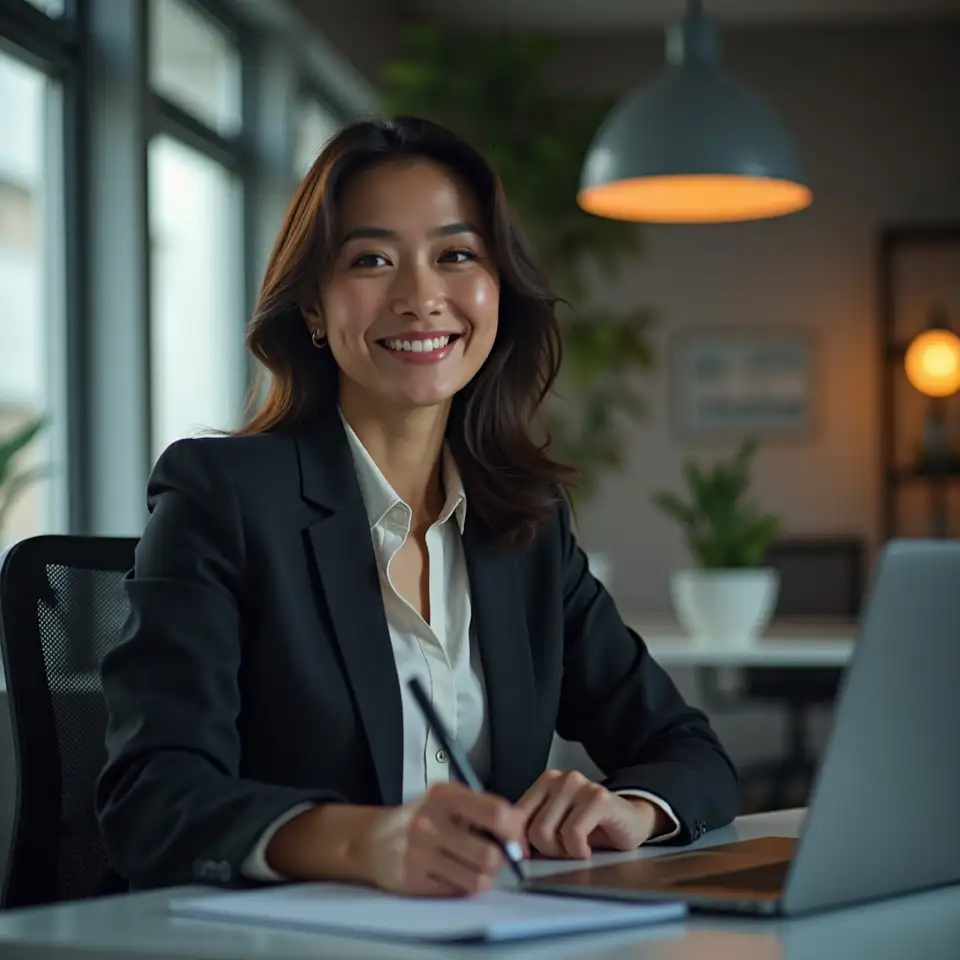
Dr. Yuki Tanaka-Reeves, Quantitative Methods Advisor
Quantitative Methods Advisor and Regulatory Economist
Dr. Tanaka-Reeves brings a regulatory economics perspective to the advisory board, having worked with financial oversight bodies examining the adequacy of internal risk models under stress scenarios. Her expertise in distributional assumptions and tail risk estimation complements the platform's core focus on CVaR, particularly in the context of Australian regulatory frameworks for institutional allocators. She advises on the boundary between model sophistication and model opacity.
Tail Risk Estimation
Regulatory Economics Framework
Distributional Assumption Analysis
Professor Alistair Nguyen-Fairweather, Mathematical Finance Chair
Mathematical Finance Chair and Academic Liaison
Professor Nguyen-Fairweather holds a chair in mathematical finance at an Australian research university and serves as the platform's primary academic liaison. His research spans stochastic optimization, coherent risk axiomatics, and the theoretical underpinnings of robust portfolio construction. He ensures that Faeleimlemlyo's content remains anchored to the current state of the academic literature, while his long experience supervising doctoral research informs the platform's commitment to precise, well-motivated exposition.
Stochastic Optimization Research
Risk Axiomatics Theory
Robust Portfolio Construction
Recognition from the Research Community
Faeleimlemlyo's contributions to applied quantitative risk methodology have drawn acknowledgment from academic and professional bodies across the region.
2025
Best Applied Risk Research Platform
Recognized by the Australian Quantitative Finance Society for clarity and depth in presenting CVaR optimization methods to a practitioner audience, bridging the gap between academic derivation and operational implementation in a rigorous and accessible manner.
Australian Quantitative Finance Society
2024
Academic Citation Excellence Award
Cited by multiple peer-reviewed journals in mathematical finance for the quality of methodological exposition on the Rockafellar-Uryasev reformulation, with reviewers noting the platform's role in disseminating technically demanding content to a broader professional audience.
Journal of Risk Research
2023
Risk Education Contribution Prize
Awarded by the Risk Management Association of Australia in recognition of sustained, rigorous contributions to practitioner understanding of coherent risk measures, tail risk estimation, and the practical application of convex optimization within institutional portfolio contexts.
Risk Management Association Australia
2022
Methodology Transparency Commendation
Commended by the Financial Analysts Forum for transparent and complete disclosure of model assumptions, scenario generation procedures, and solver-specific implementation details — setting a standard for honesty in quantitative methods communication within the Australian finance community.
Financial Analysts Forum
2021
Emerging Research Platform Recognition
Selected as a notable emerging resource in quantitative risk by the Asia-Pacific Computational Finance Network, recognizing the platform's commitment to mathematical precision and its contribution to raising the standard of applied risk methodology discussion in the region.
Asia-Pacific Computational Finance Network